The Conventional View: Scale Is the Safe Choice
For most of the last decade, the mainstream answer to peptide supplier selection criteria has been simple: rank capacity first. Tier-1 CDMOs and the procurement playbooks built around them treat production scale, reactor volume and site count as the primary de-risking signals, on the reasoning that only a large manufacturer can guarantee supply when demand spikes.
That view earned its place. Capacity scarcity through the GLP-1 era was real, and the suppliers who committed capital early genuinely solved a supply problem. CordenPharma’s roughly €900 million peptide expansion, announced in July 2024, added large-scale manufacturing trains in Colorado plus a European greenfield site. Bachem’s Building K, its large-volume Bubendorf plant, anchored CHF 332.6 million of FY2025 investment and completed the stated shift from CDMO to CMO toward industrial-scale, high-volume output.
Scale was never the wrong answer. It is simply no longer the only one.
Why Scale Stopped Being the Differentiator
Capacity has stopped separating suppliers because everyone is buying the same capacity at the same time. When several CDMOs commission large-scale peptide plants in the same window, the constraint that used to sort the field becomes a shared cost base rather than a shared advantage. Three problems follow from treating scale as the safe choice.
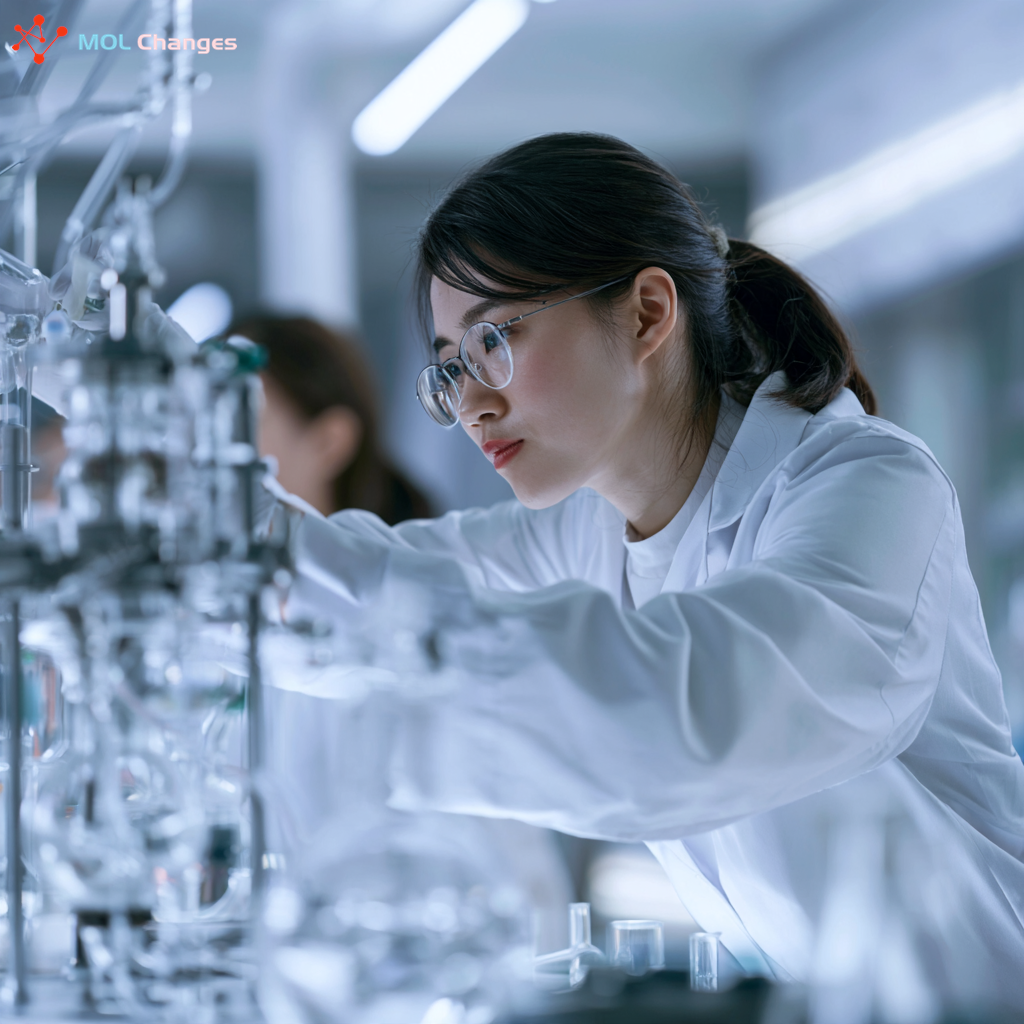
The first is that building capacity is capital-expensive and dilutive before it is accretive. Bachem’s EBIT margin fell to 22.0% in FY2024 from 22.4%, which the company attributed to “increased depreciation and amortization on new investments” in its FY2024 results release. The pattern repeated in the first half of 2026, when the company stated that “ramp-up costs for Building K affected the operating result as expected” in the most recent interim report. New capacity costs margin before it earns any.
The second problem is that where growth did arrive, it came from utilization and mix rather than from scale itself. Bachem’s Commercial API growth in the first half of 2025 was “mainly driven by a good operational execution across our network that led to an optimized utilization of existing facilities,” according to Bachem’s H1 2025 results. Filling existing plants better, not owning more of them, moved the number.
The third problem is that the breadth argument is thinner than headline growth suggests. GenScript’s FY2025 revenue rose 61.4%, but GenScript’s FY2025 results attribute that mainly to license revenue, chiefly LaNova sublicensing, while ProBio’s 309.1% growth is distorted by one-time items and fee-for-service grew 21%. Headline percentages here measure deal timing, not service capability.
When every serious player buys the same capacity, peptide supplier selection criteria shift to what capacity cannot buy: responsiveness, specialized modifications, analytical transparency, and technical collaboration.
What the Data Actually Shows About Peptide Supplier Selection Criteria
Read the disclosed numbers again and the picture inverts. GenScript’s H1 2026 interim results put total revenue at roughly US$404.2 million, up 27.3% year over year on a comparable basis; the FY2025 results report US$959.5 million and 66,000+ active Life Science Group customers. Those are service-line breadth figures. None of the GenScript results pages read for this comparison discloses a peptide-specific revenue line, capacity figure or turnaround benchmark, and that side of the comparison rests on thinner public disclosure than the Bachem side. The absence is the finding.
Bachem’s H1 2025 results show net sales of CHF 313.0 million, up 30.2%, and an EBITDA margin of 29.1%, up from 23.1% a year earlier. Growth of that shape came from better utilization of facilities Bachem already runs, not from new capacity.
Four criteria carry the weight instead: responsiveness, specialized peptide modifications, peptide analytical data transparency, and peptide CDMO technical collaboration. The evidence behind each is qualitative where the market data is thin.
|
Criterion |
What the buyer inspects |
چيليٽنگ پيپٽائيڊس Weak answer |
Strong answer |
|---|---|---|---|
|
Responsiveness |
Method transfer and pilot-batch scheduling |
ڪسٽم پيپٽائيڊس Multi-month slot queues, high MOQs |
Named transfer window, ڪيمسٽري پيپٽائڊس تي ڪلڪ ڪريو pilot-to-kilogram path |
|
Specialized modifications |
Modification portfolio and sequence complexity handled |
Catalog-only list |
Specific modification types with precedent |
|
Analytical transparency |
CoA fields and method documentation |
Purity percentage alone |
Method, column, and lot-to-lot comparability data |
|
Technical collaboration |
Scale-up handoff and transfer support |
Handoff at purchase order |
Documented transfer plan across mg to kg |
Criterion 1 and 2: Responsiveness and Specialized Modifications
These two criteria are measured in elapsed time and chemistry classes, not in tonnes. Responsiveness means method-transfer and pilot-batch lead time; specialized modifications means whether a supplier can hold a non-standard chemistry through scale-up.
On responsiveness, the structural contrast is utilization. Bachem’s H1 2025 results describe growth as coming from utilization of existing facilities rather than new capacity, which is the pattern buyers meet as slot scheduling and high MOQs on early-stage pilot batches. GenScript’s FY2025 results disclose no turnaround benchmark on the pages reviewed, so published lead times remain a qualitative range: roughly two to three weeks for standard sequences and three to six weeks for complex ones, figures that appear mainly in commercially motivated sources and should be treated as a range, not a market statistic.
For custom peptide synthesis capabilities, evaluate by chemistry class rather than service bullets. پيگيليشن, cyclization, glycopeptides and isotope labeling each carry different failure modes, and the question is whether the supplier holds the modification through scale-up. Four sequence properties predict difficulty: hydrophobicity and aggregation tendency, chain length, multi-site modification, and disulfide topology. Each maps to a capability, not a catalog entry.
ٽپ لاء: Run the buyer-side evaluation sequence in order: difficult-sequence feasibility check, then
specialized peptide modificationscapability check, then analytical package review, then the scale-up and tech-transfer conversation.
Criterion 3: Analytical Transparency Is the Hardest Claim to Fake
Analytical transparency is the one criterion a buyer can verify before committing, which makes it the highest-signal screen in the framework. A batch certificate of analysis is not proof on its own. What matters is whether it carries the fields a filing needs: an HPLC chromatogram with the method and column conditions, an MS spectrum confirming the expected mass, a purity figure tied to a defined method, and a stated endotoxin result.
Endotoxin thresholds tighten with the assay, and the default specification rarely matches the application. One testing-vendor resource reports that levels below 1.0 EU/mg are generally acceptable for immortalized cell lines, below 0.05 EU/mg for primary immune cells, and 0.1 جي طرف 0.5 EU/mg for in vivo rodent studies, with USP 〈85〉 injectable limits set at 5 EU/kg/hr on a different unit basis (Creative Proteomics endotoxin and sterility testing resource, undated). That is a single vendor source, and the USP 〈85〉 figure should be re-verified against the chapter itself before it anchors a specification.
The honest limitation: USP’s 〈1503〉 chapter on synthetic peptide quality attributes and the ICH Q6B framework for justified specifications could not be read in full text in this pass, so the documentation argument here rests on supplier-side and secondary material rather than the standards themselves.
Criterion 4: Technical Collaboration and the Scale-Up Handoff
Technical collaboration is what decides whether responsiveness, modifications and analytical transparency survive the jump from pilot to commercial batch. A supplier can look strong at milligram scale and still fail the handoff: purity drifts, batch-to-batch comparability weakens, and the receiving team inherits a method it cannot reproduce. Peptide CDMO technical collaboration is therefore a selection criterion, not a courtesy.
MOL تبديليون, as one example inside this framework, describes the two sourcing extremes it positions against: “choosing either a single tier-1 contract development and manufacturing organization (CDMO) or relying exclusively on a low-cost, unverified catalog supplier. Both extremes introduce systemic risk.” The same page states Peptide ڪيميائي that a warm second source, kept alive through minor annual order allocations, cuts emergency supplier transition timelines from 12 months to under 3 weeks. Treat that as the brand’s stated service model, not an independent benchmark; the operational case for a warm second source rests on the buyer’s own continuity planning.
The cheap alternative fails in a predictable place. Suppliers promising rapid turnaround often lack cleanroom sterility controls, robust analytical instrumentation, or lot-to-lot batch comparability, which is exactly the documentation a commercial batch needs. Peptide Synthesis Companies
How to Apply the Framework
Start by sending a supplier the sequence that actually gives you trouble, not a catalog peptide. A trial synthesis on your real difficult sequence is the fastest way to see whether the responsiveness claim holds, and it takes days rather than a full evaluation cycle. Isotope ليبل ٿيل Peptides
-
Send the difficult sequence for a trial synthesis. Days. This is the quickest filter you have.
-
Request the modification list with named chemistries. Ask which of them survive scale-up, not just which appear in a brochure. Quick win.
-
Request a real batch CoA and read the method fields, not only the purity number. Quick win.
-
Open a tech-transfer conversation covering the mg to kg path and the documentation handoff. Longer-term.
-
Qualify a warm second source with a minor annual allocation. Longer-term, and the step most buyers skip until an emergency forces it.
Scoring sheet: carry the four criteria (responsiveness, specialized modifications, analytical transparency, technical collaboration) into the supplier call as a one-page grid, and score each answer against the artifact you were shown.
Measure the framework by method-transfer elapsed time, batch-to-batch comparability, and whether the analytical package clears your filing review without follow-up queries. Those three signals are the operational lever behind Bachem’s H1 2025 results, where utilization, not catalog breadth, moved the margin line. Expect the first three steps to change your shortlist within one evaluation cycle.
Caveats: Where the Conventional View Still Holds
For a late-stage commercial program with fixed, multi-year demand, tier-1 scale and a regulatory track record genuinely reduce risk, and the four criteria above do not replace that. Slot scheduling and minimum order quantities bite hardest at development and early-clinical scale, which is where this framework applies most strongly.
Two limits are worth naming. The GenScript side of this comparison rests on thinner public disclosure than the Bachem side, so part of the asymmetry may reflect disclosure practice rather than capability. And Bachem’s margin compression is self-declared as planned and transitory, a fairer framing than margin pressure alone; the company’s stated 2026 ambition of more than CHF 1 billion in sales and over 30% EBITDA margin, as of the H1 2025 release, is not the profile of a supplier losing ground.
The claim is not that scale is worthless. It is that scale has stopped being sufficient on its own.
اڪثر پڇيا ويا سوال
But doesn’t a tier-1 CDMO’s scale protect us if demand spikes?
Scale protects the supplier’s throughput, not your queue position. The company’s stated 2026 ambition at large CDMOs is to fill capacity with programs already holding reserved slots, so a spike is exactly when an unreserved buyer waits longest. The protection you want is a warm second source with a reserved slot, not a bigger primary.
What if we have already qualified a large supplier and switching is expensive?
You do not have to switch. Qualify a second source alongside the incumbent, which is what the operational case for a warm second source describes: minor annual allocations keep the relationship and the documentation current, so an emergency transition is a phone call rather than a fresh qualification. The incumbent keeps the volume; the second source keeps you covered.
How do you respond to the argument that boutique suppliers cannot support commercial volumes?
That argument conflates a boutique’s catalog business with its custom peptide synthesis capabilities. GenScript’s FY2025 results show how license-driven growth qualification works at scale, and the same qualification logic applies downward: what matters is whether the supplier can document method transfer, lot comparability and scale-up continuity, not whether its name is large. Ask for the transfer record, not the headcount.
Isn’t analytical transparency just a matter of asking for the CoA?
نه. A CoA is a summary; peptide analytical data transparency is whether the underlying method, the lot it was run on and the specification it was judged against travel with the number. Endotoxin thresholds tighten with the assay, so a certificate that reports a value without the method and limit tells you little. Ask which assay, which lot, which specification, and whether peptide CDMO technical collaboration extends to reviewing the data with you.
Conclusion: What Buyers Should Ask For in 2026
Scale is now table stakes in peptide supplier selection criteria, and the four criteria that actually separate suppliers are responsiveness, specialized modifications, analytical transparency and technical collaboration. Bachem’s H1 2026 results make the point: net sales rose 4.3% to CHF 326.4 million while the EBITDA margin fell 3.7 percentage points to 25.4% (Bachem’s H1 2026 results, July 2026). Capacity growth no longer guarantees pricing power or service quality.
So ask for artifacts, not assurances. Request a representative CoA with the analytical method behind each specification, a written list of modifications the supplier has actually delivered, and a named technical contact who owns the scale-up handoff. Where suppliers publish nothing comparable, treat the gap as a finding: GenScript’s FY2025 results show how little peptide-specific disclosure reaches buyers who need to compare (GenScript’s FY2025 results). The market improves when the CoA, the modification list and the transfer path become the comparison surface.
If you are evaluating suppliers now, request a representative CoA package and a technical consultation before you commit to a slot.
This article is published by MOL Changes, which offers custom peptide synthesis and analytical documentation services. Consider that interest when weighing the framework above.